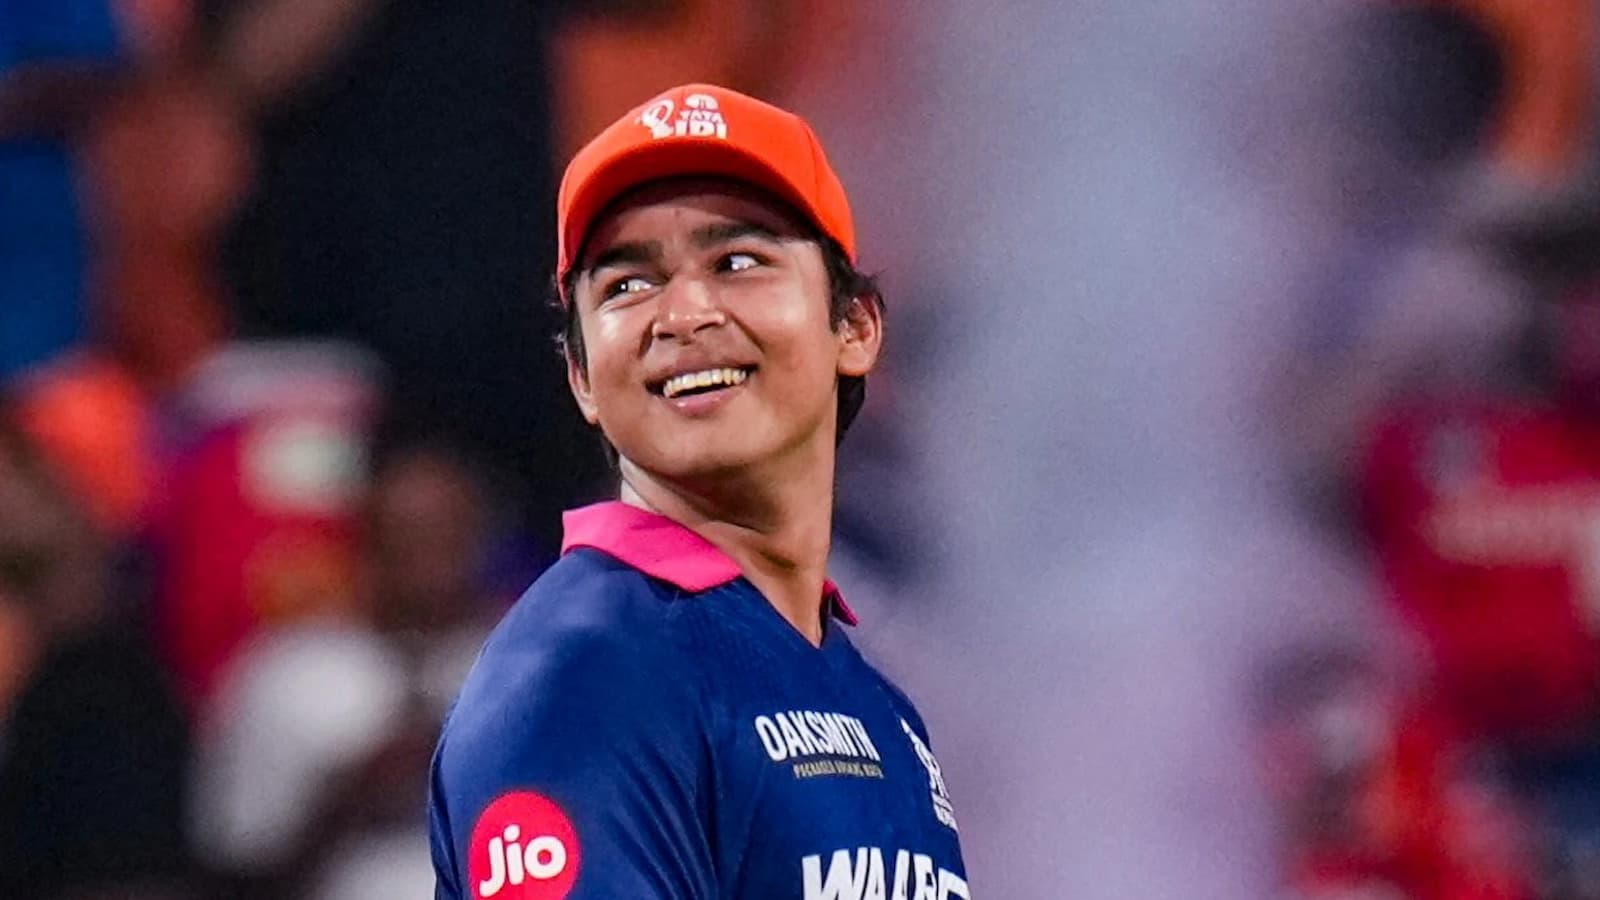
Income Tax for Minors in India: Teen cricket star Vaibhav Sooryavanshi is now being talked about not only for his batting, but also for his money. Recent reports say his estimated net worth is around ₹7 crore at just 15 years old. A lot of that money comes from cricket, like IPL pay, league money, and brand deals. The latest Mint report on June 1, 2026 also said some estimates put his net worth even higher when match fees and endorsements are counted.
When a child earns money, who pays the tax? In India, the answer depends on how the money was earned. The law has one set of rules for normal minor income and another set for income that comes from the child’s own skill or hard work.
LTCG Tax Exemption on Joint Property: Can Both Spouses Claim the Benefit?
What the Tax Law says for Minors
Under Indian tax law, a minor is a person who has not completed 18 years of age. In most normal cases, a minor’s income is not taxed separately. It is added to the income of the parent whose own income is higher, and then taxed in that parent’s hands. The Income Tax Department says this rule comes from Section 64(1A).
The official portal also says there is a small relief of up to ₹1,500 per child under Section 10(32) when a minor’s income is clubbed with a parent’s income. So if a child earns income from things like bank interest or fixed deposits, that money is usually added to the parent’s tax return, after the allowed exemption is taken out.
There are also some special cases.
- If both mother and father earn, the minor’s income is added to the return of the parent who has the higher income.
- If the parents are divorced, the income is added to the income of the parent who has custody of the child.
- If both parents are not alive, the minor’s income is not clubbed with a guardian’s income, and a separate return is filed for the child.
When a Minor must File a Separate Return
The tax rule changes when the child earns money through his or her own skill, talent, knowledge, or manual work. In that case, the income is taxed in the child’s own name and is not clubbed with the parent’s income. That is why income from cricket, acting, singing, content creation, reality shows, and similar work is treated differently. The Income Tax Department itself says income from manual work or from skill, knowledge, talent, experience, and similar effort is not clubbed with the parent.
June 1 Rule Changes: How New Tax, UPI and LPG Updates Will Impact Your Money?
Pranav Sai S said, “This exception applies because the income arises from the minor’s personal efforts and abilities rather than from assets or funds transferred by a parent,” said Pranav Sai S, tax expert at ClearTax.
For filing, the return is usually reported under business or profession income when the activity is professional in nature. In such cases, ITR-3 is generally used. ITR-4 can be used when presumptive taxation conditions are met. The return is filed in the minor’s name through a parent or legal guardian acting on the child’s behalf. The Income Tax Department’s e-filing help pages also show that a guardian can register and act for a minor.
The Disability Exception
There is one more important exception. If a minor has a disability covered under Section 80U, the income is not clubbed with the parent at all. The Income Tax Department says this rule applies to a minor child suffering from disability specified under Section 80U, and official tax materials describe this as a person with disability at the 40% level or more, with a separate severe disability category too.