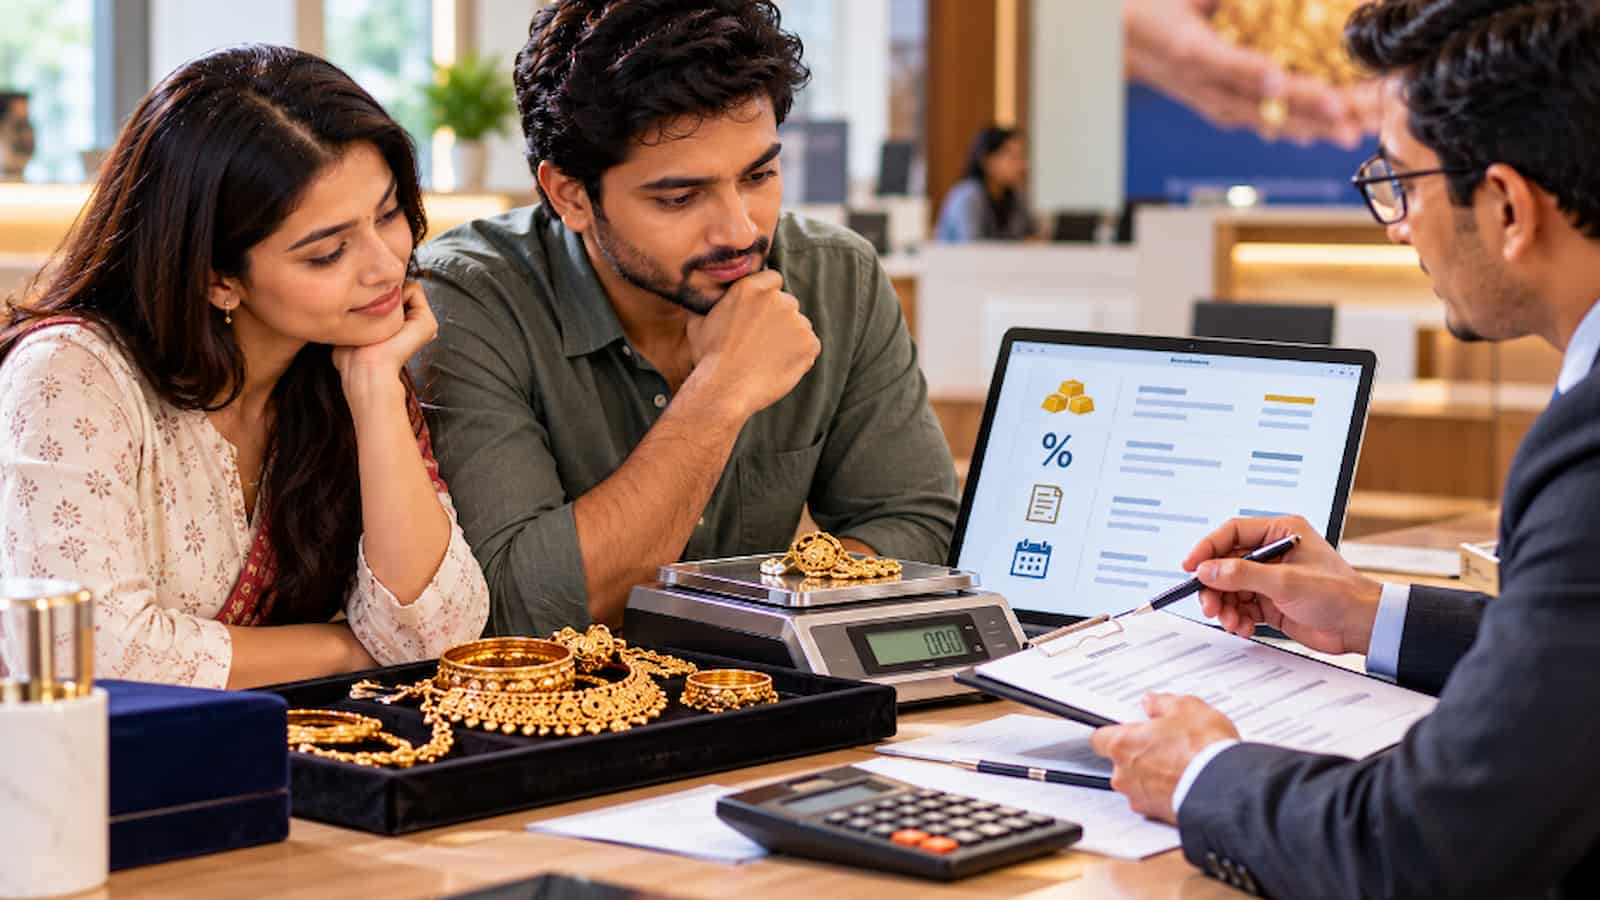
A gold loan can help you access funds without selling your jewellery. Before pledging your gold, check its purity, eligible weight, assessed value, loan-to-value ratio (LTV), interest rate, charges and repayment terms.
The amount you can borrow depends on the value of eligible gold after its purity and weight are assessed. The total cost of the loan depends on the applicable interest rate, repayment period and charges. Checking these details before applying can help you borrow an amount that fits your financial needs.
How is your gold loan amount decided?
Your loan amount is based on the value of eligible gold you pledge, not simply the total weight of the jewellery or the price you originally paid.
The lender assesses the gold based on factors such as purity and net eligible weight. The applicable valuation method and LTV limit are then used to determine the maximum eligible loan amount.
This means two pieces of jewellery with the same gross weight may not have the same loan value if their purity or non-gold content differs.
Why should you check the gold rate?
Gold prices change regularly because of market conditions, international prices, currency movements and other factors. However, the retail gold rate you see in a city is not necessarily the same as the rate used to value gold for a loan.
For example, gold rates may differ across markets such as Delhi, Mumbai, Jaipur and other cities. For loan valuation, the applicable rate is determined using the lender’s valuation process and the relevant regulatory requirements.
Bajaj Finance uses the lower of the previous day’s closing price or the 30-day average closing price for the relevant purity, as published by the IBJA or a SEBI-regulated commodity exchange.
You can check today gold rate in India to understand the prevailing market price. But do not assume that the retail rate alone determines your loan amount.
Does all your jewellery weight count?
The gross weight of jewellery does not necessarily represent the amount of gold considered for loan valuation.
Jewellery may contain stones, enamel, beads or other materials. These are not treated as gold when determining the eligible value.
For example, if a necklace weighs 30 grams but contains stones and other non-gold components, the entire 30 grams may not be considered eligible gold weight. The final value depends on the net eligible gold content and its purity.
This is why checking how the jewellery will be assessed is important before deciding how much to borrow.
Why does gold purity matter?
Purity indicates how much actual gold is present in the jewellery. Higher purity generally means a higher gold content for the same weight. The table below shows the gold content at different purity levels.
| Purity | Gold content |
| 18 karat | 75% |
| 22 karat or 916 | 91.6% |
| 24 karat | 99.9% |
For gold loans, eligible jewellery is generally assessed within the applicable purity range. Gold coins may have different purity eligibility subject to the lender’s terms. For a Bajaj Finance Gold Loan, jewellery with a purity of 18 to 22 karats is eligible. Gold coins of up to 24 karats may also be accepted, subject to applicable terms.
Therefore, do not estimate your loan amount using weight alone. Purity and eligible net weight both affect the assessed value.
How does LTV affect the amount you can borrow?
LTV, or loan-to-value ratio, shows the maximum proportion of the assessed gold value that can be offered as a loan.
For the applicable Bajaj Finance Gold Loan limits:
| Loan amount slab | Maximum LTV |
| Up to Rs.2.5 lakh | 85% |
| More than Rs.2.5 lakh to Rs.5 lakh | 80% |
| More than Rs.5 lakh to Rs.2 crore | 75% |
For example, if your assessed gold value is Rs.2 lakh and the applicable LTV is 85%, the maximum amount based on that LTV would be Rs.1.70 lakh.
This is an eligibility ceiling, not a recommendation to borrow the maximum amount. Your final sanctioned amount can also depend on the lender’s assessment, eligibility and applicable terms.
What interest rate should you check?
The interest rate directly affects the cost of borrowing. Bajaj Finance Gold Loan interest rates currently range from 9.50% to 24.25% p.a., depending on the applicable terms.
Do not compare loans only by looking at the headline rate. Check how the interest is charged, when it is payable and whether other charges apply.
A lower interest rate can reduce borrowing costs, but the actual cost also depends on the amount borrowed, repayment period and applicable fees.
Which charges should you check?
Interest is only one part of the borrowing cost. Before applying, check all applicable charges such as processing fees, stamp duty and more.
Other charges may apply depending on the service or situation. Check the applicable schedule of charges before accepting the loan offer so that you know the total cost you may have to pay.
How does repayment affect your borrowing cost?
The repayment structure should match your expected cash flow. A loan may appear affordable at the time of borrowing but become difficult to manage if the repayment schedule does not fit your income.
Under bullet repayment, both the principal and interest due are paid at maturity. Under regular repayment, interest is paid at half-yearly intervals as per the repayment schedule, while the principal is paid at maturity.
Before pledging your gold, check:
- When interest payments are due
- When the principal must be repaid
- The loan tenure
- The amount payable at maturity
- What happens if repayment is delayed
Choosing a repayment structure you can manage is as important as checking the eligible loan amount.
Can you estimate your gold loan before applying?
A gold loan calculator can help you estimate a possible loan amount and understand how changes in gold value or loan requirements may affect the estimate. For example, you can compare different loan amounts and repayment scenarios before deciding how much you actually need to borrow.
However, a calculator gives an indicative estimate. It does not guarantee a sanctioned amount because the final loan depends on the actual assessment of your gold, eligibility, applicable LTV and other terms.
What documents do you need for a gold loan?
The documents required can depend on the lender and application. Typically, borrowers may need identity and address proof along with other documents required for the application and verification process.
If you are applying for a gold loan in Delhi, Mumbai, Jaipur, Bengaluru, Chennai, Hyderabad, Pune or Kolkata, check the current document requirements before visiting a branch. Similar requirements may apply across other cities, subject to the lender’s terms.
Keeping the required documents ready can make the application process smoother.
What should you check before taking a gold loan?
Use this checklist before pledging your jewellery:
| Check | Why it matters |
| Purity and net weight | Determines the eligible gold content |
| Gold valuation | Helps establish the assessed collateral value |
| LTV | Determines the maximum eligible loan against that value |
| Interest rate | Affects the borrowing cost |
| Processing and other charges | Adds to the total amount payable |
| Repayment schedule | Helps you plan interest and principal payments |
| Loan tenure | Affects how long the gold remains pledged |
| Final repayment amount | Helps you assess affordability |
Do not decide only on the maximum amount you can borrow. First calculate how much you actually need and whether you can repay it within the agreed terms.
What should you remember before pledging your gold?
A gold loan decision should start with the value of your eligible gold and the amount you actually need, not just the maximum amount available.
Check the purity and net weight, understand how the gold is valued, review the applicable LTV, compare the interest rate and charges and choose a repayment structure that fits your cash flow. You can also use a calculator to test different borrowing scenarios before applying.
Whether you are considering a gold loan, the key questions remain the same: How much is my eligible gold worth, how much do I need to borrow, and can I comfortably repay the loan?