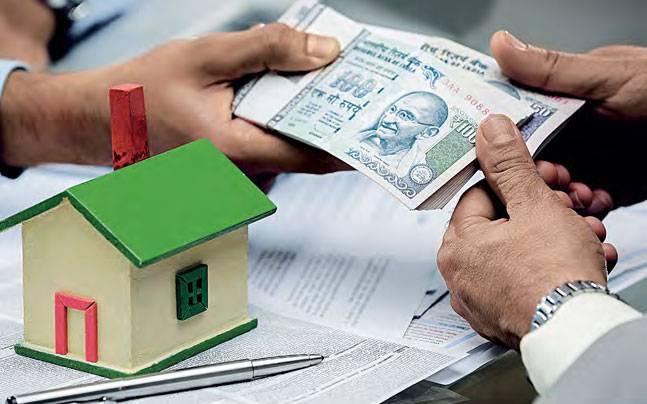
Home Loan Tax Benefits: A lot of people think they can’t get tax benefits on both rent and home loan payments. But that’s not true. If you are following the old tax regime, then yes you can claim tax benefits for both. You just need to understand how to do it the right way.
Many salaried people live in rented houses while also paying EMIs for a home they own somewhere else. This is a common case, and the income tax rules allow you to claim tax savings on both, as long as your claims are real and match with the proofs you give.
ITR Filing 2025-26: Four Common Mistakes Salaried Taxpayers Should Avoid
Tax Benefits You Can Get Under Old Regime
Under the old tax system, the government gives some good options to save tax if you’re paying rent and also have a home loan. These are explained under different sections of the Income Tax Act.
If You Are Paying Rent:
You can claim HRA (House Rent Allowance) under Section 10(13A). This is only for salaried people who get HRA as part of their salary. The tax exemption amount is decided based on these 3 things, and you get the lowest of the three:
-
The actual HRA you receive from your employer
-
50% of your basic salary if you live in a metro city (like Delhi, Mumbai, Chennai, Kolkata)
-
40% of your basic salary if you live in a non-metro city
-
Rent you actually pay minus 10% of your basic salary
If You Are Paying EMIs for a Home Loan:
You can also save tax on your home loan under two separate sections. Section 24(b) You can claim a deduction of up to ₹2 lakh per year on the interest part of your EMI if the house is self-occupied. And section 80C You can claim up to ₹1.5 lakh per year for the principal part of your EMI.
The best part is that these two benefits HRA and home loan deductions—are not linked to each other. So if you are paying rent and also paying EMIs for a different home, you are allowed to claim both at the same time.
When Can You Claim Both?
There are many situations when a person may live in a rented place and still pay EMIs for a different property:
-
If your house is in another city, but your job is in a different place
-
If your house is under construction and not ready to move in
-
If you have given your own house on rent and live in a rented house nearby because you needed more space
Political Donation Deductions: I-T Department Launches TAXASSIST to Aid Queries Under Section 80GGC
In all these cases, as long as the details are true and you have proper proof, the income tax department allows you to claim the benefits.
What Should You do at Year-End?
If your employer did not give full tax benefits during salary calculation or deducted more TDS, don’t worry. You can still claim the tax refund at the end of the financial year. You just need to submit the correct documents:
-
Rent receipts for your rented house
-
Interest certificate from your bank for the home loan
-
Report any rent income if you are earning from your own house
-
Use the correct ITR form that matches your income sources
If your claims are real and backed with proper documents, then the Income Tax Department will approve them and give you the refund you deserve.